Malaysia's two international financial centres, Labuan International Business and Financial Centre and Tun Razak Exchange, signed a memorandum of understanding on September 18, 2026 to strengthen collaboration and advance a “1 Ecosystem, 2 IFCs” model, bringing together Labuan's specialised cross-border financial capabilities with TRX's concentration of financial institutions, businesses and talent in Kuala Lumpur. The agreement provides for cooperation in market development, research, knowledge sharing, promotional activity and investment facilitation, with the stated objective of strengthening Malaysia's position as a regional financial gateway.
The announcement is significant because financial-centre competition is increasingly moving away from the traditional idea that investors choose one location and conduct most financial functions there. Modern businesses often distribute their financial requirements across jurisdictions and institutions. They may need corporate finance in one location, wealth management in another, insurance and risk management through another, Islamic financing through another and access to regional investors through a major capital-market centre. Malaysia's proposal is effectively an attempt to make those functions complementary.
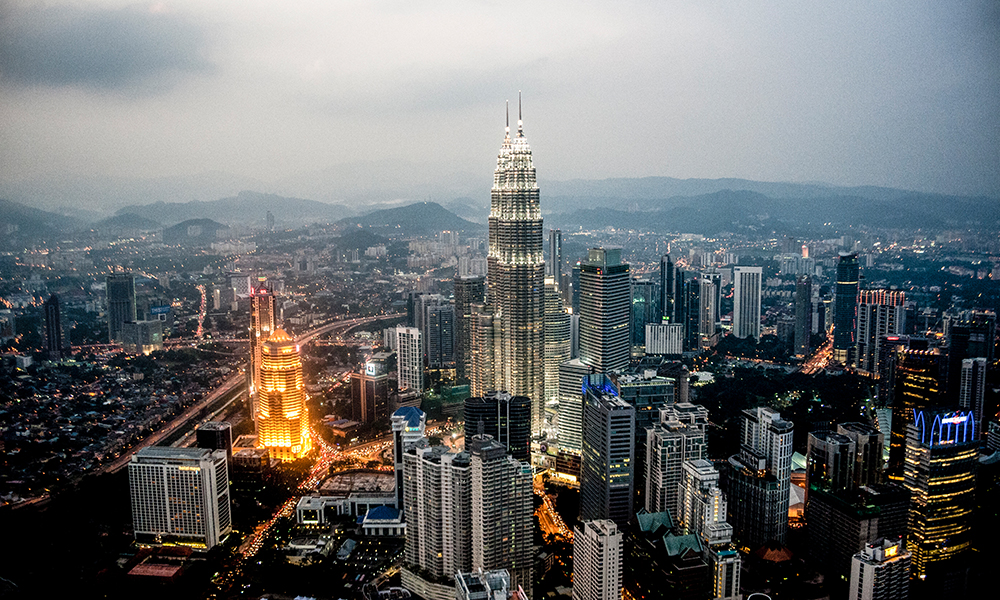
Labuan IBFC has developed as an international business and financial centre focused on cross-border activities including wealth management, investment and financing structures, insurance, Islamic finance and digital financial services. TRX, by contrast, has been developed as Malaysia's International Financial Centre within Kuala Lumpur, with financial institutions, multinational corporations, technology companies and professional services concentrated in a major urban financial district.
The two propositions are different, which is precisely why the September 18 agreement matters. Labuan does not need to replicate TRX, and TRX does not need to replicate Labuan.
The commercial logic is to make the distinction useful to businesses rather than allowing it to create fragmentation.
Labuan IBFC says it is home to approximately 5,000 operating companies and that its position in the Global Financial Centres Index improved from 55th to 44th among 139 centres this year. TRX, meanwhile, has more than 120 firms and approximately 30,000 workers operating across its 70- acre district.
Those numbers provide scale, but scale alone does not create an ecosystem. The real test will be whether a business can move between the capabilities of the two centres without encountering unnecessary regulatory, administrative or operational friction.
Consider a multinational company entering Southeast Asia. It might require an investment structure, cross-border treasury arrangements, insurance, wealth management, financing, Islamic financial products and access to institutional investors. If the Malaysian financial system can allow the company to use Labuan for specialised international structures while accessing TRX's institutional and capital- market ecosystem in Kuala Lumpur, the two centres become more valuable together than separately.
That is the strategic premise behind the “1 Ecosystem, 2 IFCs” proposition. It also reflects a wider shift in the geography of Asian finance. Financial centres are increasingly competing through networks. Singapore connects capital with Southeast Asia, Hong Kong connects international investors with mainland China and the wider Asian market, Dubai increasingly connects Middle Eastern capital with Asian opportunities, while other centres are seeking to establish specialised niches within regional capital flows.
Malaysia has a potential advantage because it can combine an established domestic economy with an international financial centre designed specifically around cross-border activity. The challenge is making those two systems easier to navigate. Regulatory clarity will be critical. Labuan entities operate under the supervision of Labuan FSA, while TRX forms part of Malaysia's broader financial and corporate ecosystem. A connected proposition cannot mean blurred
responsibilities. Investors need to understand which regulatory framework applies to a particular activity, where an entity should be established and how transactions between the two environments will be treated.
The proposed collaboration therefore needs to become operational rather than merely promotional. Joint research and market-development initiatives can build visibility, but businesses ultimately assess a financial centre through practical experience. Licensing, onboarding, banking relationships, professional services, foreign exchange, dispute resolution and transaction execution will determine whether the connection provides genuine value.
Islamic finance could become one area where the model has particular relevance. Labuan has established capabilities in Islamic financial services, while Malaysia has a broader national ambition around Islamic finance. Connecting those capabilities with TRX's institutional ecosystem could strengthen Malaysia's ability to serve investors and issuers seeking Shariah-compliant financial structures across Asia and the Middle East.
Digital finance presents another opportunity. Labuan has been strengthening its regulatory framework around digital money broking, while TRX increasingly hosts technology and financial-services businesses. The combination could allow Malaysia to present digital finance within a broader
institutional ecosystem rather than as a standalone technology proposition.
“The significance of the Labuan-TRX initiative lies in connecting complementary capabilities rather than attempting to make two financial centres identical,” FSCL said. “International businesses increasingly need access to several financial functions across several markets, and a connected ecosystem can reduce the friction involved in arranging those services. The commercial value will depend on how effectively businesses can move between the two centres while maintaining regulatory clarity and operational certainty.”
For investors, the same principle applies. “Financial-centre connectivity has to be measured through the client experience,” FSCL said. “If the connection makes it easier to access capital, structure transactions, manage risk and obtain specialised financial services, it can strengthen Malaysia's regional proposition. If businesses encounter duplicated processes or uncertainty about which framework applies, the theoretical advantage of two connected centres will be harder to translate into commercial value.”
The development also comes at a time when capital flows between Asia and the Middle East are becoming increasingly important. Malaysian institutions and companies are seeking international capital, while investors from the Gulf and other regions are looking for Asian opportunities. A financial
ecosystem capable of serving both sides of that relationship could potentially become a useful intermediary.
There is also an important talent dimension. TRX's concentration of financial professionals, multinational businesses and technology companies creates a different form of value from Labuan's specialised international financial infrastructure. Connecting those communities could improve the movement of expertise as well as capital.
The broader concept is therefore less about geography than financial architecture. A company should not have to choose one location for every financial requirement if different locations offer distinct advantages. What matters is whether those advantages can be accessed through a coherent system.
Malaysia's two-centre model will now face the more difficult stage of implementation. The MoU creates a platform for collaboration, but the market will determine whether that collaboration becomes meaningful. Investors will ultimately look for evidence that the arrangement improves access, reduces friction and expands the range of financial solutions available to businesses.
The September agreement is therefore best understood as an attempt to reposition Malaysia's financial geography.
Labuan and TRX remain distinct centres, but their value may increasingly be judged by the strength of the connections between them.
If that connectivity becomes practical, Malaysia could offer international businesses something more useful than a choice between two financial centres. It could offer an ecosystem in which each centre performs a different role within the same regional financial strategy.